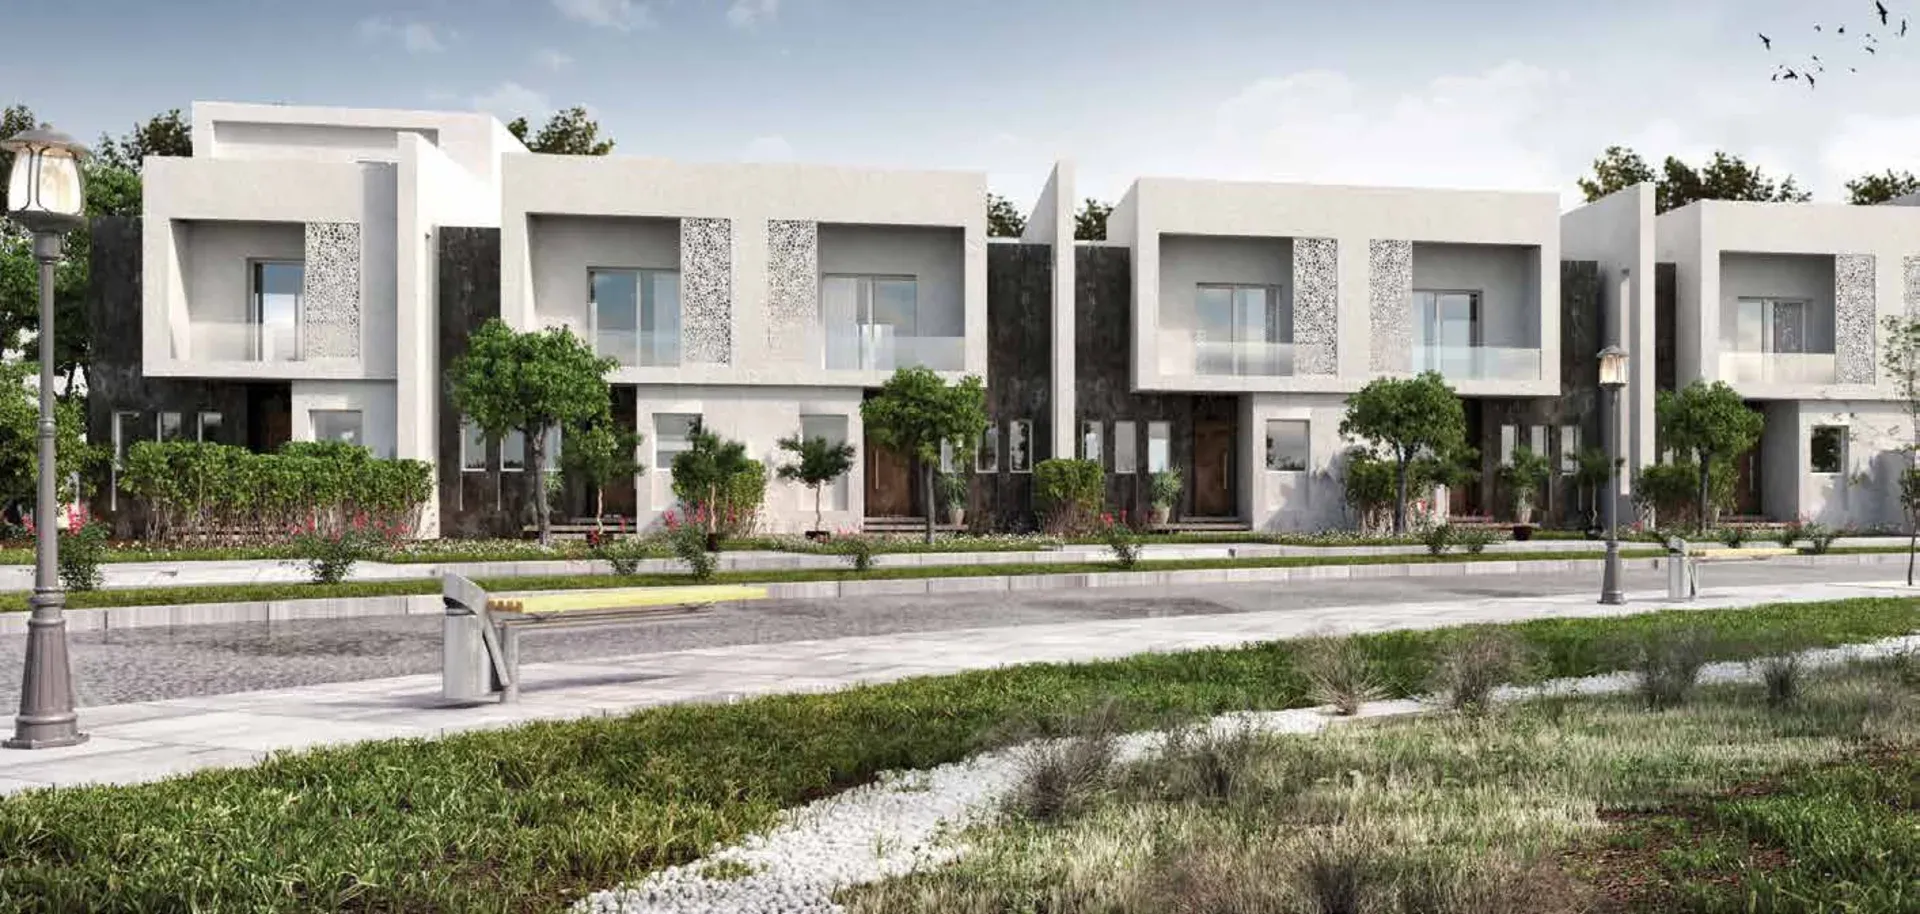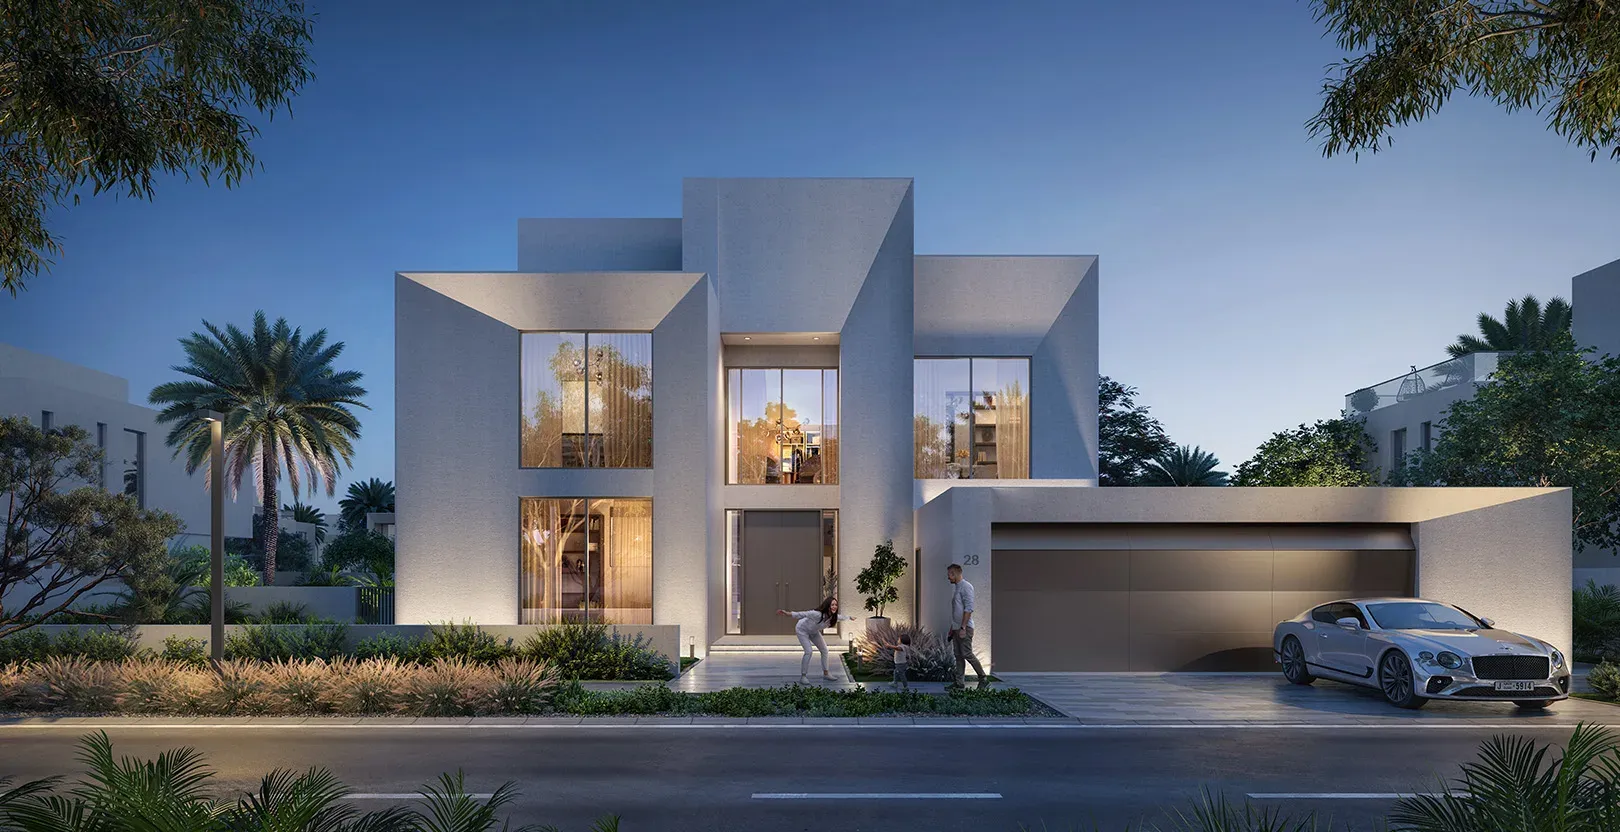
This guide covers the villa districts the headline belts overshadow. Dubailand's family corridor, Dubai Islands and Dubai South each carry enough product for standalone guides — we've written those separately — so what follows is the rest of the city: six zones, every community that matters in each, and the launch-to-2026 arithmetic that tells you which zones still owe their owners a re-rating. Two ground rules from our research: asking prices are not sold prices, and a community's DLD district name is the only location that counts — half the mislabelled listings we corrected came from brokers borrowing a more famous neighbour's address.
Investment Guide
The Dubai Villa Map 2026: Every District Worth Knowing, Zone by Zone
Ask ten brokers where to buy a villa in Dubai and you'll hear the same six names. The city actually holds more than forty villa and townhouse districts — from AED 1.1M townhouse pools to AED 425M private-island records — and the best value regularly hides in the ones the guides skip. GRAF mapped all of them: ~250 sources, launch prices against 2026 transactions, and the ownership traps nobody mentions until it's too late. Here is the whole city, zone by zone.

Dubai villa map
Where Dubai's villa districts actually sit
Every district named in this guide is a marker on the map — all fifty-one, including the ones with no GRAF project page and the ones we flag as traps. Click a marker, or any row, for the project page where one exists. Coordinates are verified against external mapping services and brokerage listings, community by community — not placed by eye on the district.
- 01 Palm Jumeirah Coast & private islands · the benchmark AED 18–55M
- 02 Palm Jebel Ali Coast & private islands · the buyable palm from AED 18M
- 03 Palm Central Palm Jebel Ali · private residences from AED 4.9M
- 04 Jumeirah Bay Island Coast & private islands · ~18 deals a year ~AED 8,500/sqft
- 05 The World Islands Coast & private islands · Amali-dominated avg deal AED 115.7M
- 06 Pearl Jumeirah Coast & private islands land to AED 5,205/sqft
- 07 Sur La Mer Jumeirah 1 · the freehold pocket in a GCC-only belt AED 4.8–26.5M
- 08 Bay Villas Dubai Islands · Island B from AED 4M
- 09 Emirates Hills Emirates Living · records at AED 425M avg deal AED 75.2M
- 10 The Meadows Emirates Living · +29.4% y/y 3-bed ~AED 10.5M
- 11 The Lakes Emirates Living · the 2003 freehold experiment resale market
- 12 The Springs Emirates Living · launched from AED 448,888 3-bed ~AED 5.9M
- 13 Jumeirah Islands Emirates Living · +153%/sqft, Dubai's strongest customs to AED 82M
- 14 Jumeirah Park Emirates Living · launched from AED 2.4M in 2006 avg sale AED 9.1M
- 15 Jumeirah Heights Emirates Living · 4-bed townhouses do not exist duplex niche
- 16 Jumeirah Golf Estates Golf west · metro at the gate AED 5.7–54M
- 17 Victory Heights Golf west · beside the Els Club 4-bed median AED 8.85M
- 18 Al Furjan Value south · two metro stations, psf +65% from AED 2.9M (2021)
- 19 Jebel Ali Village Value south · 2021 relaunch, up 50–150% from ~AED 4M
- 20 Green Community DIP Value south · verify freehold street by street title patchwork
- 21 The Sustainable City Value south · proof that good communities plateau −4.4% y/y
- 22 Verdana Value south · cash-discount townhouses cheapest new-build
- 23 Dubai Hills Estate Green centre · the liquid blue-chip Sidra ~AED 9.5M
- 24 Al Barari Green centre · +52.7% y/y, 2026's sharpest move avg AED 23M
- 25 Sobha Reserve Wadi Al Safa 2 · 300+ standalone villas from AED 8.15M
- 26 District One Green centre · Meydan lagoon, +17% y/y avg AED 20.8M
- 27 Nad Al Sheba Gardens Green centre · launched from AED 3.43M in 2023 resale AED 6.1M+
- 28 MAG Eye · Millennium Estates Meydan · the centre's value corridor from ~AED 3.1M
- 29 District 11 — The Fields Meydan · Opal Gardens & The Sanctuary AED 2.48–4.53M
- 30 Eden Hills MBR City · phase-one villas from AED 17.5M
- 31 Canal Front Residences Dubai Water Canal · complete and trading ready stock
- 32 The Valley East · up 130–187% since 2019 AED 2.6–2.8M
- 33 Jumeirah Village Triangle East · +150–180% since 2020 2-bed AED 5.4–5.6M
- 34 Jumeirah Village Circle East · a villa market again 3-bed rows from AED 2.8M
- 35 Cedre Villas · Silicon Oasis East · the 2029 Blue Line story avg AED 7.81M
- 36 Warsan Village East · Dubai's cheapest 3-bed townhouse pool AED 1.1–2.15M
- 37 Mirdif Hills East · Mirdif is otherwise 95% GCC-only freehold exception
- 38 Living Legends East · restarted from 833/sqft in 2015 AED 5–18M
- 39 Heights Country Club & Wellness Al Qudra frontier · 81M sqft from AED 6M
- 40 Grand Polo Club & Resort Al Qudra frontier · the AED 41bn bet from AED 3.5M
- 41 The Wilds Al Qudra frontier · Aldar's mainland flagship from AED 5M
- 42 Sobha Elwood Al Qudra frontier · on the E66 AED 5–11.6M
- 43 The Oasis Al Qudra frontier · the luxury end from AED 9.18M
- 44 DAMAC Sun City Al Qudra frontier · Al Yelayiss 1 from AED 2.25M
- 45 DAMAC Islands Dubailand — NOT near DIP or Expo from AED 2.75M
- 46 DAMAC Riverside Dubai Investments Park 2 from AED 2.2M
- 47 Cherrywoods Al Qudra frontier · the corridor's delivered proof from 882/sqft
- 48 Athlon Wadi Al Safa 5 · active-living master plan from AED 2.8M
- 49 Haven Wadi Al Safa 5 · wellness community from AED 3.7M
- 50 The Acres Wadi Al Safa 7 · standalone villas from AED 5.1M
- 51 Tilal Al Ghaf Al Qudra · "Aura Gardens, Al Khawaneej" is actually here lagoon community
At a glance
The shortlist, by entry price
- 01 The coast & private islands Palm money, its half-price successor, and the one freehold townhouse pocket in Jumeirah 1 from AED 2.7M Palm Jebel Ali entry
- 02 Emirates Living belt The 2003 launch belt that returned 7–11× — and Dubai's №1 growth market from AED 3.8M 2-bed Springs
- 03 Golf west & south The only villa zone with real metro stations — and the city's quiet value plays from AED 4.2M 3-bed Al Furjan
- 04 The green centre (MBR) Dubai Hills, Al Barari, District One — where the AED 20M+ market actually trades from AED 3.1M Meydan townhouse
- 05 The east Silicon Oasis to Mirdif — schools, metro 2029, and Dubai's cheapest 3-bed pool from AED 1.1M Warsan Village 3-bed
- 06 Al Qudra frontier The 2024–25 mega-launches — five new master communities in one corridor from AED 2.49M Heights CC launch
How to read the map
Dubai's villa geography is six concentric stories. On the water: the palms and private islands, where the city's wealth concentrates. Behind Marina: the Emirates Living belt, the original 2003 freehold experiment that made early buyers 7–11× their money. Down the E311: the golf-and-value west. In the middle: the MBR green centre, today's prime market. To the east: the established family districts everyone forgets. And on the desert edge: the Al Qudra frontier, where five new master communities launched in eighteen months. Prices below are 2026 transactions or documented asking ranges — where only thin or unverified data exists, we say so.
1
The coast and private islands
Palm Jumeirah remains the benchmark: Garden Homes trade at AED 18–55M and Signature Villas from 45M to a AED 280M ask, at AED 3,500–10,000/sqft — and the reference case from our research is a villa bought for AED 2.6M in 2008 selling at 23.2M in 2024, roughly +790%. The islands beyond it are where the record books now write themselves: Jumeirah Bay averages ~AED 8,500/sqft on a market of barely eighteen deals a year (peak villa: AED 330M); World Islands trade is dominated by the Amali development (average recorded deal AED 115.7M); Pearl Jumeirah land has printed up to AED 5,205/sqft.
The buyable story is Palm Jebel Ali — Nakheel's second palm, relaunched in September 2023 from AED 18M for villas at ~AED 2,466–3,916/sqft. Resales already run 17.5–35.9M with new phases stepping higher; it is tomorrow's Palm Jumeirah priced at roughly half today's — the villa collections, real floor plans and payment schedule are on our Palm Jebel Ali page. One more coastal footnote worth knowing: the classic Jumeirah–Umm Suqeim beach belt is not freehold for foreigners (GCC-nationals-only), with rare point exceptions — Sur La Mer's 147 Italian-style townhouses (AED 4.8–26.5M) are the freehold townhouse pocket in Jumeirah 1.

Palm villa case, 2008→2024
+790%
Palm Jebel Ali launch (2023)
from AED 18M
Coastal villas
AED 3,400–10,000/sqft

Palm Jebel Ali, Dubai View Project →
More about Palm Central Private Residences Palm Central on Palm Jebel Ali
The lowest ticket onto Dubai's second palm — Nakheel beachfront at a fraction of Palm Jumeirah money, before the bridges and beach clubs land.
AED 2.7M from
70/30 1–2BR plan
Sep 2030 handover
2
The Emirates Living belt — the compounding machine
Between Sheikh Zayed Road and the E44 sit the communities that proved the freehold model: Emirates Hills (average deal AED 75.2M; records at 425M), the Meadows (3-beds ~10.5M, +29.4% year-on-year), the Lakes, and the Springs — whose launch price is one of the few in the city that survives in print: from AED 448,888 in the Gulf News archives. A Springs 3-bed today trades around AED 5.9M: a 7–11× return over two decades, before rent.
The zone's 2026 headline is Jumeirah Islands: +153% per sqft since May 2021 — the strongest villa appreciation in Dubai — driven by a knock-down-and-rebuild market where custom homes reach AED 82M. Jumeirah Park behind it (launched from 2.4M in 2006, average sale now 9.1M) and the duplex niche of Jumeirah Heights round out the belt. This zone is about proven streets and grown trees; you pay for certainty, and the growth still hasn't stopped.

Springs launch (2003, documented)
AED 448,888
Springs 3-bed today
~AED 5.9M
Jumeirah Islands psf since 2021
+153%
3
Golf west and the value south
West along the E311, golf anchors the market: Jumeirah Golf Estates (villas AED 5.7–54M around the Earth and Fire courses, with its own metro station at the gate — a villa-zone rarity) and Victory Heights beside the Els Club (4-bed median AED 8.85M, basket up 21–51% year-on-year in Q1 2026). The value story sits closer to the port: Al Furjan, served by two metro stations, where Murooj launched at AED 2.9M in 2021 and the community's median psf has climbed 65% since; and Jebel Ali Village, whose 2021 relaunch villas (from ~AED 4M) are up 50–150%.
Honest flags for the zone: Green Community DIP is attractive and mature, but title there is a leasehold-vs-freehold patchwork — verify the specific street against DLD before you offer; and Sustainable City, after its pioneering rally, printed −4.4% year-on-year — proof that even good communities plateau. The budget south (Verdana's cash-discount townhouses, Warsan-style pools) is the cheapest new-build villa money in Dubai, with liquidity to match.

Al Furjan Murooj launch (2021)
from AED 2.9M
Al Furjan median psf 2021→25
+65%
Metro stations in the zone
3
4
The green centre — MBR City, Dubai Hills, Meydan
The centre is where Dubai's prime villa market actually clears. Dubai Hills Estate is the liquid blue-chip: Sidra villas that launched around AED 3.6–5M in 2016 now trade near 9.5M, and Golf Place averages AED 25.3M at 2,481/sqft — up ~170% on launch. Al Barari, the low-density botanical outlier, posted the centre's sharpest 2026 move: +52.7% year-on-year, averaging AED 23M — and beside it in Wadi Al Safa 2, Sobha Reserve is now reaching handover with 300+ standalone villas from about AED 8.15M on the resale market. District One on the Meydan lagoon averages AED 20.8M with +17% year-on-year; Nad Al Sheba Gardens' newer phases (from 3.43M in 2023) already resell at 6.1M+.
Meydan itself is the centre's value corridor — MAG Eye townhouses from ~AED 3.1M and Millennium Estates at 1,869/sqft — and the District 11 cluster (The Fields, completed 2024, transactions 2.48–4.53M; Opal Gardens and The Sanctuary around the lagoon) keeps adding freehold stock. At the top of the new-launch market, Eden Hills' phase-one villas opened from AED 17.5M. For buyers who want the centre's address without the villa ticket — or who need something finished this year — the ready waterfront next to Safa Park is the outlier worth knowing: Canal Front on the Dubai Water Canal, complete and trading today.

Golf Place average deal
AED 25.3M
Al Barari, H1 2026
+52.7% YoY
District One average
AED 20.8M

Dubai Water Canal, by Safa Park View Project →
More about Canal Front Residences Canal Front Residences by Meydan
The centre's rarest combination — completed waterfront beside Safa Park, minutes from Downtown, at a price the off-plan towers around it will struggle to beat.
AED 3.33M from
ready move in now
completed handover
5
The east — the districts everyone forgets
East Dubai is where families who work the DXB side of the city actually live, and it hides real numbers. The Valley on the E66 is the standout: Eden launched in 2019 around AED 1.0–1.2M for 3-beds at ~625/sqft; today the community trades from 2.6–2.8M — up 130–187%, among the best documented launch-to-2026 runs in the city (full Valley page). JVT and JVC, the twin triangles, quietly became villa markets again (JVT 2-bed villas at AED 5.4–5.6M, +150–180% since 2020; JVC 3-bed rows from 2.8M). Silicon Oasis pairs Cedre Villas (average AED 7.81M) with the 2029 Blue Line metro story. And Warsan Village beside International City is Dubai's cheapest 3-bed townhouse pool: 942 identical homes at AED 1.1–2.15M.
The rest of the east reads as a caution list: Mirdif is 95% GCC-only (Mirdif Hills is the freehold exception), Al Khawaneej and the north-eastern belts are local markets closed to foreign freehold, Falconcity is thin, and Living Legends — restarted from 833/sqft in 2015 — now trades villas at 5–18M. The east's engine is Academic City's universities, Mirdif's schools and the coming metro — an end-user demand base the west never sees.

Eden (The Valley) launch 2019
~AED 1.0–1.2M
The Valley since launch
+130–187%
JVT 2-bed villas
AED 5.4–5.6M

Al Rowaiyah, beside Silicon Oasis View Project →
More about Tilal Binghatti Tilal Binghatti
The east's first-mover play — Binghatti's debut villa community with swimmable lakes, priced before the Blue Line metro opens and the big guides catch up.
AED 4.2M 4-bed villa from
20/40/40 payment plan
2028–29 handover
6
The Al Qudra frontier — five mega-launches in eighteen months
The desert corridor between Arabian Ranches and Emirates Road is where developers placed their 2024–25 bets, all at once: Emaar's Heights Country Club & Wellness — 81M sqft whose 2024 townhouse wave opened at AED 2.49M and whose current standalone-villa wave (Serro, Serro 2, Salva) starts at AED 6M for 2030 handover — and the AED 41bn Grand Polo Club & Resort, where townhouses open at AED 3.5M and villas at AED 5.5M; Aldar's The Wilds (~1,700 villas, 3-beds from AED 5M, its first Dubai mainland flagship); Sobha Elwood on the E66 (4–6-bed villas, ~AED 5–11.6M); Emaar's The Oasis at the luxury end; and DAMAC's trio — Sun City (from 2.25M), Islands and Islands 2 (from 2.75M) and Riverside in DIP2 (from 2.2M). Cherrywoods (completed 2022, transactions from 882/sqft) is the corridor's proof that delivered product here holds value.
Two things to hold onto when buying the frontier: construction on several of these had not started as of mid-2026 — you are buying a masterplan and a payment plan — and the corridor will hand over tens of thousands of homes into the same 2028–2030 window, which is a renters' market in the making before it becomes an owners' one. Entry pricing and phase discipline decide everything here; it is also where the projects in our Dubailand family-villa coverage cluster.

Heights CC launch (2024)
from AED 2.49M
The Wilds 3-bed (2025)
from AED 5M
DAMAC Islands 2 (2025)
from AED 2.75M

Al Qudra frontier, Dubailand View Project →
More about The Heights Country Club & Wellness The Heights Country Club & Wellness
The anchor of the corridor this section is about — 81M sqft, whose townhouse wave opened at AED 2.49M in 2024 and whose current standalone-villa wave sets the frontier's benchmark.
AED 6M villas from
80/20 payment plan
2030 handover
Title traps and phantom projects
The research behind this guide corrected the same errors again and again, so put them on record. Ownership: the Jumeirah/Umm Suqeim beach belt, Mirdif (bar Mirdif Hills), Al Warqaa and the north-east are GCC-only — a foreigner cannot buy the villa a portal happily advertises; Green Community DIP title must be DLD-verified street by street; Dubai Festival City's Al Badia villas are largely lease-held, not open resale. Geography: DAMAC Islands is in Dubailand (Al Yelayiss 1), not near DIP or Expo, whatever the listing says; "Aura Gardens, Al Khawaneej" is actually in Tilal Al Ghaf. Phantoms: 4-bed Jumeirah Heights townhouses don't exist (the phase was cancelled), and villa-branded apartment towers are everywhere — when the "villa" has a floor number, it's a flat. The market context that makes all this worth navigating: villa prices are still rising as the wider market cools from peak gains — the districts with real scarcity keep outperforming.
Choosing your zone
- Trophy capital, thin markets: the islands — Jumeirah Bay, World Islands, Palm Jumeirah's top end; or Palm Jebel Ali while it's still priced as a promise.
- Proven streets, school-run life: Emirates Living or Dubai Hills — pay the certainty premium; it keeps compounding.
- Growth at a discount: Jumeirah Islands' rebuild market, Al Furjan's metro corridor, JVT/JVC's villa rows, The Valley's second act.
- Ready homes, central address: the Meydan corridor — MAG Eye, Millennium Estates, or completed canal-front stock.
- First-owner pricing on the frontier: Heights CC, The Wilds, Elwood — or the east's Tilal Binghatti before the metro re-prices the corridor.
For the belts this map deliberately skips, see our dedicated guides: Dubai Islands villas, Dubai South villas and the family villa areas ranking. Where GRAF fits: behind every number here is a research file with its sources — launch archives, DLD histories, the ten-broker location checks. Tell us your budget, your zone shortlist and your timeline, and we'll answer with transactions, not adjectives. Every villa project on this map that we currently sell is listed, priced and dated on the off-plan villas page.